Sentiment edges slightly higher in August but Irish consumer mood still subdued
Posted on: 28 Aug 2026
-
Households economic and financial outlook remains negative
-
Choppy monthly changes in sentiment continue as consumers struggle with rapid and repeated changes in economic conditions
-
Could higher Government spending really make Irish consumers worse off?
-
Confidence measures diverge on either side of the Atlantic
-
Special questions focus on changes in consumer spending and incomes
-
Higher prices driving increased spending on necessities while consumers cut back outlays in other areas
-
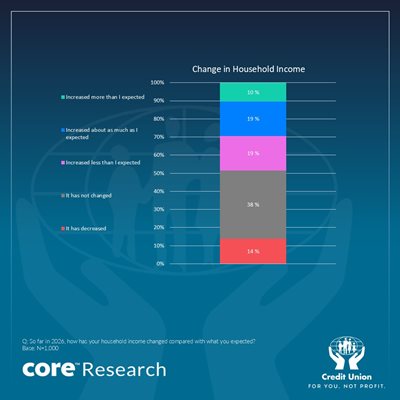
Only one in ten consumers says their income has grown faster than expected in 2026…
-
…but one in five say their income has risen less than expected, two in five say their income hasn’t changed and one in seven say their income has declined
Speaking on the release of the August sentiment survey, David Malone, CEO of the Irish League of Credit Unions noted ‘The slight uptick in consumer sentiment is welcome but the general tone of the August survey highlights the financial challenges facing many Irish households at present. For guidance and support through the entire range of positive and negative financial circumstances facing consumers today and every day, members know they can rely on the guidance and support of their local credit union.’
Summary
Irish consumer sentiment improved modestly in August but that was enough to raise it to its best level since February 2026, just before the War on Iran began.
However, the general tone of the August sentiment survey still suggests that Irish consumers are nervous about the general economic outlook and negative about their own financial circumstances.
The August survey period was notable for comparatively few notable economic developments and, with weather remaining exceptionally good, it may be that many consumers took something of a short ‘holiday break’ from what continue to be serious economic and financial concerns.
Similarly positive monthly changes in consumer confidence were reported for the Euro Area and the UK in spite of ongoing increases in motor fuel prices whereas US consumer sentiment fell significantly on increased worries about the outlook for activity and inflation.
Section I; Sentiment survey signals slightly reduced consumer concerns in August
As the table below indicates, the Credit Union Consumer Sentiment Survey (in partnership with Core Research) shows a small and statistically insignificant improvement to 63.2 from 61.6 in July. However, this was sufficient to bring sentiment to its highest level since February before the war on Iran started.
Recent months have seen small but choppy changes in sentiment as Irish consumers struggle to assess the impact on their economic and financial circumstances of rapid and repeated changes in geopolitical conditions centred on hifting prospects of peace or further devastation in the Middle East.
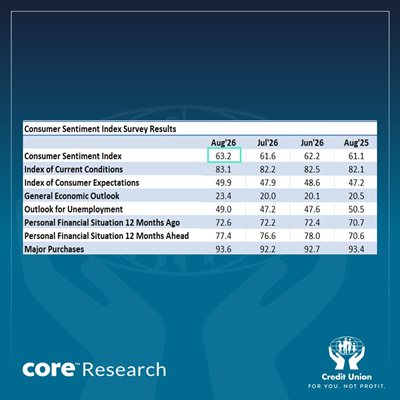
The August 2026 sentiment survey reading continues to lie some considerable distance below the long-term survey average of 83.1 or the most recent ten-year average of 76.1. As such, it suggests Irish consumers are nervous about the economic climate and negative about their own household finances.
However, it should be noted that the current sentiment reading of 63.2 is not markedly poorer than the latest five-year average of 64.1 and is slightly above the twelve-month average of 60.8. In that respect, it signals that current financial pressure on Irish consumers has been in place for some time. This suggests this pressure is sustained as well as substantial.
Sentiment diverges on either side of the Atlantic in August
In common with the Irish sentiment survey results, consumer confidence improved in both the Euro area and the UK in August. However, there was a significant weakening in sentiment in the US, which the authors of the US sentiment report note was focussed on worries about the outlook for activity and inflation.
While the drop in US consumer sentiment was broadly-based in August, the survey authors note that it was particularly pronounced among older and lower-income households, suggesting that cost-of-living concerns remain influential.
Motor fuel costs rose on both sides of the Atlantic in August. So, variations in this area don’t explain the divergence in sentiment readings. Our tentative reasoning is that economic news has been more worrisome in the US through the latest survey period, with weaker payroll data and higher interest rates among the more notable developments.
In contrast, Euro area economic activity data have been more resilient than expected of late, with business survey indicators showing the fastest pace of expansion in nine months in August while GDP increased at a healthy pace in the second quarter and employment continued to grow. Although inflation ticked higher in August, this largely reflected higher energy prices as food price inflation eased and ‘core’ inflation held steady.
While Euro area consumer confidence improved modestly in August, the current reading (-15.6) is still some distance below either its long-term average (-10.9) or the level seen in February (-12.1) prior to the war on Iran.
In contrast, UK consumer confidence increased materially in August to its best level in two years. The authors of the UK report note significant gains in consumer thinking about the economic outlook, their own financial prospects and the current buying climate.
Our sense is that this improvement in UK consumer confidence owes much to a ‘Burnham bounce’ as the new Prime Minister announces initial measures to ease cost of living pressures and promises a ten-year plan to transform the UK. Viewed from this perspective, it will be interesting to see how UK sentiment negotiates the rough and tumble of the Budget process in coming months.
Irish consumer sentiment improves in August; broadly-based or thinly-spread?
All five elements of the August reading of the Credit Union Consumer Sentiment Survey (in partnership with Core Research) showed improvements compared to July. The scale of these increases varied significantly, with ‘macro’ elements showing larger if still modest monthly gains relative to those elements of the survey focussed on household finances.
The largest month-on-month gain in the August survey was in relation to the general economic outlook. We would make three points in this regard.
First of all, it is likely relevant that there were relatively few domestic economic releases of note through the August survey period. This dearth of developments coupled with normal vacation-time may mean that many Irish consumers enjoyed a ‘holiday break’ from the normal routine of reports highlighting downside risks to the economy and household living standards.
In addition, it should be noted that the most significant domestic publication since the July survey period concluded was the Summer Economic Statement. This underlined the continuing resilience of the Irish economy and the related capacity to undertake significant public spending increases and taxation adjustments in the upcoming October Budget. At the margin, the related emphasis on income tax adjustments also likely highlighted the priority the Government attaches to addressing cost-of-living difficulties.
The third point worth making in relation to consumer thinking on Irish economic prospects is that, although the August survey shows a clear if modest improvement, the current reading still suggests that consumer thinking, on balance, is still signalling expectations of a weakening in Irish economic conditions in the next twelve months.
The second strongest monthly improvement in the August survey was in relation to the jobs market. Again, it should be emphasised that consumer thinking on the jobs market has been particularly weak of late and this remains the case even after a small improvement in August.
The absence of further notable layoff announcements through the August survey period may have contributed to a slight bounce in this element of the survey but the broader message is that consumer thinking on the outlook for jobs remains understandably pessimistic.
Irish consumers not quite as nervous in August
All three elements of the sentiment survey dealing with personal finances showed marginally less negativity in August than in July, although these latest readings underscore continuing and substantial worries about consumers’ own personal financial circumstances.
It should be noted that Irish retail energy prices rose between July and August but we previously suggested that this uplift might have been widely anticipated in the July sentiment reading.
Moreover, we would imagine that an ongoing slowdown in food price inflation, down to 0.7%y/y in July and flat over the past three months, may also have helped Irish consumer thinking on living costs.
Finally, the signalling of upcoming fiscal support to household spending power in the Summer Economic Statement likely cushioned the blow of rising energy prices somewhat.
Will fiscal measures make Irish consumers worse off?
In light of repeated references to a significant negative impact from Government spending measures on household living costs, it may be worth considering whether Irish consumers are completely foolish to want some fiscal support in the upcoming Budget.
Our reading of the details of the Central Bank research that has been cited in this regard is that they might paint a much less threatening picture in this respect than has frequently been suggested. It may be worth looking at this area, particularly as further recent commentary in this regard may weigh on sentiment next month.
From the outset, it is extremely important to emphasise that this Central Bank research is extremely valuable in terms of contributing to our understanding of Irish economic dynamics and it is clearly the case that the research adheres to best practices. The focus here is on the way some elements of the results have been presented (not by the Central Bank) in some media commentaries.
A 2024 Central Bank article (Fiscal Priorities for the Short and Medium Term) examined the impact of a faster pace of public spending on various Irish economic metrics. It should be emphasised that this model-based exercise simulated the impact of faster Government spending on the Irish economy rather than assessing what impact it actually had.
Using a macro-model, the simulation posits that higher Government spending boosts demand in the economy and thereby leads prices to move higher than they would if demand were weaker. Importantly, it is the stimulus to spending power in the economy that causes the boost to prices. In other words, higher prices are a result of stronger activity and increased spending power rather than a net drain on spending power.
This exercise suggested that, relative to a baseline scenario, consumer prices would be somewhat higher than would otherwise be the case. Importantly and perhaps surprisingly, omitted from some work and commentary referring to this, the Central Bank research also estimated that the positive impact on domestic economic activity was nearly four times larger than the impact on prices (page 20 cited above). So, in all likelihood, the faster pace of Government spending would have boosted the average household’s real income much more than it raised their living costs in recent years.
Equally importantly, given media commentary, the 2024 Central Bank research did not at any point deduce that higher Government spending had actually boosted the average Irish household’s living costs by €1,000. Nor is there clear supporting evidence from consumer price data for this oft-repeated assertion.
The starting date in the Central Bank’s simulation is 2022. Over the period between January 2022 and July 2026, Irish consumer prices rose by a cumulative 22.3% making it the 21st fastest increase in prices of the EU 27 over this period, suggesting no marked boost to Irish inflation beyond global trends from the oft-quoted reference to the rapid pace of growth in Irish Government spending relative to our EU peers.
It might be added that while 'elevated' increases in Irish Government spending have not seen any marked underperformance in Irelands inflation, they have coincided with a clear Irish outperformance of growth in activity and employment in recent years. It might also be added that the ongoing step-up in Investment spending may be boosting Ireland's economic capacity and thereby serves to reduce inflation.
After the August 2026 sentiment survey concluded, the Irish Fiscal Advisory Council’s Pre-Budget Assessment report (Pre-Budget-2027-Statement-website.pdf) inferred from more recent Central Bank research (2026 Fiscal Article) that ‘If budgetary policy continues in line with recent years, it will add to inflation. Boyd et al. (2026) show that if government spending grows by 9% per year rather than 5% per year, the price level would be 1.7% higher by 2030. For an average household, this would equate to a cumulative increase of €1,000 in annual outgoings’.
The latest IFAC analysis doesn’t include any assessment of the associated favourable boost to household spending power from the Central Bank’s estimates that imply the increase in economic activity from higher Government spending would be more than three times as large as any impact on consumer prices.
It might be suggested that the tone of much of the commentary on this issue is analogous to someone complaining that they may have to spend more than €1,000 extra on transport costs to move to a new job but omitting to mention that the new job is expected to boost their take-home pay by €3,000 to €4,000.
Section II; Irish consumers still struggling with higher living costs
As usual, the August 2026 Credit Union Consumer Sentiment Survey (in partnership with Core Research) included supplementary questions on topics of current interest.
For the August survey, we asked whether they had increased or reduced their spending in various areas and why this was the case. We also asked how their income had changed relative to what they had expected.
We first asked whether consumers were spending more now than a year ago across some of the key areas of household outlays. The results are shown in the diagram below.
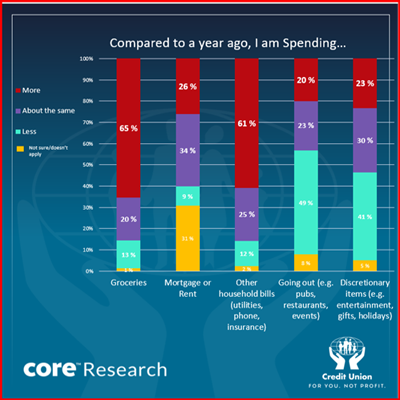
The diagram above suggests that 65% of Irish consumers are spending more now than a year ago on necessities such as food and a broadly similar 61% of consumers are spending more on household bills while there is also a marked trend towards reduced spending on going out and purchases of discretionary items.
Increased spending on groceries is the most common experience across all demographics in the past year but the proportion increased notably among those aged over 45. This response was also positively correlated with income whereas those saying they were facing difficulty making ends meet were more than twice as likely to say they had cut back spending on groceries than those without problems in this regard.
The sense of a spillover from price pressure in specific areas such as groceries into more broadly based increases in living costs is suggested by 61% of consumers who indicated their outlays on other household bills were now higher than a year ago.
Again, these results were broadly based across demographics but the incidence of increased outlays on household bills was notably more pronounced among older age groups. In contrast to responses on groceries, those with difficulty making ends meet were notably more likely to say they had increased spending on household bills than those without such problems.
This result could be because poorer or more financially stretched households may be more likely to live in less energy-efficient homes, they might face more limited choice in the suppliers they can use and/or they may be using older or less efficient household equipment or transport. Any or all of these factors could be translating into less favourable trends in household bills for these households.
While most consumers say they are spending more on necessities now than a year ago, relatively few are spending more on discretionary items and going out, while notably larger numbers say they have cut back spending in these areas.
Again, nearly all key demographics report greater numbers cutting back than increasing spending, a result that likely reflects the broadly based nature of the pressure on living costs.
However, the share of those cutting back rose with age and was altogether more pronounced among those with difficulties making ends meet. Indeed, in the one exception to this result, those without problems making ends meet were as likely to say they have spent more on discretionary items as they were to say they have cut back.
Why do consumers say their spending has changed this year?
We also asked consumers to indicate why they felt their spending had changed in a particular direction through the past year. Set out in the diagram below are responses from consumers who said their spending in various areas had increased in the past year. The figures towards the top of the graphic give the number of consumers in each category who said their spending in that category had increased in the past year.
The responses shown in the diagram below clearly indicate that higher prices are far and away the principal reason why Irish consumers feel their spending has increased in the past year across most of the major areas of household outlays.
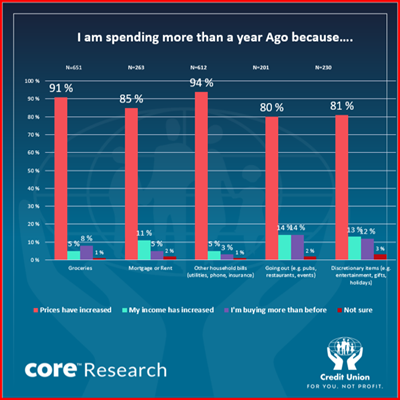
The emphasis on higher prices is overwhelming in relation to spending on groceries and household bills but also dominates massively in relation to going out and discretionary spend.
It should be noted that consumers could give more than one response to this question. Hence the totals add to more than 100%. However, the nature of the results (ie responses on groceries add up to just 105%) underscores the singular influence of higher prices.
Do consumers think their incomes are rising in 2026?
Finally, we also asked consumers how their incomes had evolved relative to their expectations. The latest official data show that in the first three months of 2026 aggregate household incomes were 4.2% higher than a year earlier. When account is taken of increases in population or in the number of households (or inflation), this implies significant numbers of consumers could have seen reductions in their income over that period.
As the diagram below illustrates, upside surprises to household incomes have been far less pronounced than the pressure on living costs.
Only one-in-ten consumers say their income has increased faster than expected while nearly twice as many consumers (19%) say their income has risen less than expected. Nearly two in five consumers say their income hasn’t changed this year while a material one in seven consumers (14%) say their income has fallen.
Very limited numbers of consumers in most demographics indicated that their incomes had risen faster than expected but there were comparatively more of those aged 25 to 34 and of those on very low incomes who gave this response while there were relatively few consumers aged over 65 in this category.
Relatively few of those aged over 55 were likely to say their incomes had risen less than expected but comparatively more than younger age groups were likely to say their income hadn’t changed.
Notably more females than males indicated that their incomes had declined while those with difficulty making ends meet were more than twice as likely as others to say their income had fallen.
The broad message from the August sentiment survey special questions is that higher prices are causing Irish consumers to spend more on necessities and cut back in other areas while income growth has largely disappointed this year.
The Credit Union Irish Consumer Sentiment Survey is a monthly survey of a nationally representative sample of 1,000 adults. Since May 2019, Core Research have undertaken the survey administration and data collection for the Survey. This tranche of the survey was live between the 4th and 19th August 2026.